Stablecoin Payments for UAE Businesses: Benefits, Regulations and Risks
Stablecoin payments offer UAE businesses new possibilities for cross-border settlements and financial operations. Explore commercial benefits, CBUAE regulations, compliance risks, and practical steps before adoption.
Key takeaways
- Stablecoin payments may improve international settlement efficiency, but commercial benefits depend on the complete payment process.
- UAE businesses cannot automatically accept every stablecoin for goods and services because CBUAE restrictions apply.
- Dubai VARA, ADGM FSRA, and CBUAE frameworks have different regulatory responsibilities.
- AML controls, cybersecurity, issuer reliability, and accounting procedures are central to stablecoin payment risk management.
- UAE SMEs should confirm legal permissibility, provider authorisation, and financial feasibility before implementation.
- KPM Global Services UAE can support accounting, documentation, financial reporting, and operational readiness assessments.
Stablecoin Payments for UAE Businesses: Benefits, Regulations and Compliance Risks
Stablecoin payments are attracting attention from UAE businesses seeking more efficient ways to manage international transactions, supplier payments, and digital financial operations.
For companies operating in Dubai, Abu Dhabi, and other Emirates, stablecoins may provide advantages such as faster blockchain transfers, improved transaction visibility, and opportunities to automate certain financial processes.
However, accepting stablecoins is not simply a matter of creating a digital wallet or integrating a payment gateway.
UAE businesses cannot automatically accept every stablecoin as payment for goods or services.
The Central Bank of the UAE (CBUAE) regulates payment-token activities under its Payment Token Services Regulation. Other authorities, including Dubai's Virtual Assets Regulatory Authority (VARA) and the Financial Services Regulatory Authority (FSRA) of Abu Dhabi Global Market (ADGM), may also be relevant depending on the business jurisdiction and activity.
For business owners, CFOs, and finance teams, the central question is whether stablecoin payments provide meaningful commercial benefits within a legally permissible and financially manageable structure.
What Are Stablecoin Payments and How Do They Work?
Stablecoin payments involve transferring digital tokens designed to maintain a relatively stable value against a reference asset, commonly a traditional currency such as the US dollar or UAE dirham.
Unlike cryptocurrencies whose market prices can fluctuate significantly, fiat-backed stablecoins are designed to follow the value of their underlying currency. Their stability, however, depends on the issuer, reserve arrangements, redemption rights, and market conditions.
A typical stablecoin payment process involves several stages.
Stablecoin Acquisition
The payer obtains an appropriate digital token through a service provider authorised for the relevant activity.
Token Transfer
The payer transfers the stablecoin to the recipient's designated digital wallet using a supported blockchain network.
Blockchain Confirmation
The blockchain network processes and records the transaction, providing an identifiable transaction reference.
Conversion or Retention
Depending on applicable regulations and business arrangements, the recipient may convert the token into conventional currency or retain an authorised balance.
Accounting Reconciliation
The finance team records the transaction, matches it with the supporting invoice, and reconciles any conversion proceeds or fees.
Although blockchain transfers may settle quickly, the complete process can involve banking procedures, compliance checks, and currency conversions.
For UAE businesses, the legal status of the token and its intended use should be established before implementing this process.
Why Are UAE Businesses Exploring Stablecoin Payments?
UAE businesses are examining stablecoin payments because international transactions can involve banking delays, intermediary institutions, currency conversion costs, and complicated reconciliation procedures.
Stablecoin infrastructure may help address certain payment challenges, particularly for businesses dealing with overseas suppliers, international customers, or regulated digital-asset markets.
Cross-Border Transactions
Companies operating internationally may explore stablecoins where conventional payment arrangements involve several banks or payment providers.
International Supplier Settlements
Businesses purchasing goods or services from overseas counterparties may investigate alternative settlement arrangements when payment delays affect operations.
Digital Business Models
Technology companies, financial platforms, and other businesses operating within approved digital-asset ecosystems may find particular applications for token-based transactions.
Treasury Operations
Businesses with international financial activities may consider stablecoins as an additional settlement mechanism, subject to regulatory permissions and internal treasury policies.
However, the commercial value of these applications depends on actual transaction costs, settlement efficiency, and the company's ability to manage the associated risks.
Example 1: Dubai Technology Company
A fictional Dubai-based technology company regularly purchases software development services from suppliers in different countries.
Its management considers stablecoin payments because some international bank transfers involve several processing stages and currency conversion charges.
Before proceeding, the company examines whether the proposed payment structure is permitted under applicable UAE rules. Its finance team also reviews provider authorisations, conversion charges, wallet security, and accounting requirements.
The assessment helps management compare stablecoin settlement with conventional banking arrangements rather than assuming the newer technology will automatically be more efficient.
What Are the Main Benefits of Stablecoin Payments for UAE Businesses?
Stablecoins may offer faster blockchain transfers, improved transaction traceability, flexible settlement arrangements, and opportunities for financial automation. These advantages can be relevant to businesses handling international payments or operating in approved digital-asset environments. However, the actual benefit depends on regulatory permissions, conversion arrangements, transaction costs, and operational controls.
Faster Cross-Border Settlement
One attraction of stablecoin payments is that blockchain networks can operate outside conventional banking hours.
This may be useful for UAE businesses dealing with customers and suppliers across multiple time zones.
However, 24-hour blockchain availability does not guarantee immediate access to money in a corporate bank account.
Conversion providers, compliance procedures, and traditional banking systems may still affect the settlement timeline.
Finance teams should measure the entire process, from the payer's initial transfer to the final availability of funds.
Potential Reduction in Payment Costs
Stablecoin transfers may reduce certain intermediary costs in specific international payment arrangements.
However, a low blockchain transaction fee does not necessarily mean that the overall payment is inexpensive.
Businesses may incur network charges, exchange spreads, custody fees, conversion costs, withdrawal charges, and compliance expenses.
The appropriate financial comparison is the total cost of a completed stablecoin transaction against the cost of an equivalent bank transfer.
Better Transaction Visibility
Blockchain networks generally maintain transaction records that can be inspected using relevant network tools.
These records may show wallet addresses, transferred amounts, transaction references, and confirmation details.
Such visibility can assist finance teams when tracking payments or investigating reconciliation differences.
Nevertheless, a wallet address does not automatically identify the individual or organisation controlling it.
Businesses still require appropriate counterparty documentation and transaction verification.
Opportunities for Payment Automation
Some stablecoin payment arrangements can interact with software systems and smart contracts.
This creates potential applications in automated settlements, approved supplier disbursements, and transaction reconciliation.
For example, a permitted payment process could be linked to a verified business milestone or approved financial instruction.
However, automation introduces additional risks, including software vulnerabilities, incorrect payment instructions, and unauthorised transfers.
Effective implementation requires approval limits, cybersecurity safeguards, and clear responsibility for financial controls.
Greater Treasury Flexibility
Stablecoins may provide an alternative settlement mechanism for companies operating across several markets.
However, maintaining stablecoin balances can expose a business to issuer risk, redemption restrictions, market liquidity conditions, and custody failures.
For many businesses, converting permitted receipts into conventional currency promptly may be more appropriate than holding significant digital-token balances.
Are Stablecoin Payments Legal for UAE Businesses?
Stablecoin payments are regulated in the UAE, and their legality depends on the token, issuer, transaction purpose, business activity, and applicable jurisdiction. The CBUAE imposes specific restrictions on merchant acceptance and payment-token services. Businesses should not assume that an internationally recognised stablecoin can automatically be used to pay ordinary commercial invoices.
Central Bank of the UAE Payment Token Services Regulation
The CBUAE Payment Token Services Regulation establishes rules governing payment-token issuance, conversion, custody, and transfer within its applicable regulatory perimeter.
The framework distinguishes between Dirham Payment Tokens and Foreign Payment Tokens.
Under Article 2, merchants selling goods or services in the UAE are restricted from accepting virtual assets toward payment unless the transaction falls within specified permitted categories. The provision excludes Financial Free Zones from its definition of the UAE for this purpose.
Dirham Payment Tokens
A merchant within the applicable framework may accept a Dirham Payment Token issued by a licensed Payment Token Issuer when used as a means of payment, subject to the regulation.
Foreign Payment Tokens
The regulation provides a specific permitted use for Foreign Payment Tokens issued by registered Foreign Payment Token Issuers when purchasing virtual assets or virtual-asset derivatives.
This does not amount to general permission for UAE merchants to accept foreign-currency stablecoins for everyday goods and services.
Payment-Token Service Providers
Businesses providing regulated payment-token services, such as issuance, conversion, or custody and transfer, must obtain the relevant CBUAE licence or registration where required.
For a mainland retailer, consultancy, trading company, or e-commerce business, the distinction between accepting a permitted payment and providing a regulated financial service is particularly important.
Official source: CBUAE Payment Token Services Regulation
https://rulebook.centralbank.ae/en/rulebook/payment-token-services-regulation
How Does Dubai's VARA Framework Apply to Stablecoins?
Dubai's Virtual Assets Regulatory Authority regulates relevant virtual-asset activities across Dubai's mainland and free zones, excluding the Dubai International Financial Centre.
VARA has established rules covering Fiat-Referenced Virtual Assets, including requirements relating to reserves, disclosures, governance, redemption arrangements, and regulatory approval.
However, its framework does not replace the CBUAE's authority over AED-referenced payment tokens.
VARA's rules expressly reserve the issuance of AED-referenced stablecoins for the CBUAE's regulatory jurisdiction.
Fiat-Referenced Virtual Assets issued under VARA's framework are also restricted to permitted activity within the virtual-asset ecosystem and cannot be treated as unrestricted payment instruments for ordinary UAE goods and services.
For Dubai businesses, obtaining services from a VARA-regulated provider does not automatically establish that every proposed commercial payment is permitted.
Official source: VARA Fiat-Referenced Virtual Assets Issuance Rules
https://rulebooks.vara.ae/rulebook/annex-1-fiat-referenced-virtual-assets-issuance-rules
What Stablecoin Regulations Apply in Abu Dhabi Global Market?
Abu Dhabi Global Market operates a separate financial-services regulatory framework administered by the FSRA.
Its approach includes rules for Fiat-Referenced Tokens covering reserve management, issuer governance, redemption arrangements, disclosures, and regulated financial activities.
Amendments effective from 1 January 2026 expanded the framework for regulated activities involving Fiat-Referenced Tokens.
Under the relevant framework, Authorised Persons conducting regulated activities involving these tokens must use tokens accepted by the FSRA.
However, regulatory acceptance does not remove the need to assess reserve quality, issuer reliability, redemption terms, and financial exposure.
Businesses operating within ADGM should obtain advice based on their particular regulated activities and proposed payment arrangements.
Official source: ADGM Digital Assets Framework
https://www.adgm.com/business-areas/digital-assets
What Are the Main Compliance Risks of Stablecoin Payments?
Stablecoin payments can create regulatory, financial, operational, and cybersecurity risks. The most significant concerns include accepting an ineligible token, using unauthorised payment providers, inadequate anti-money laundering controls, unexpected changes in token value, and difficulties reconciling transactions. UAE businesses should establish appropriate controls before deploying stablecoin payment arrangements.
Regulatory and Licensing Risk
A payment structure may involve different organisations performing issuance, transfer, custody, conversion, and settlement services.
Each relevant activity should be assessed against applicable regulatory requirements.
Businesses should verify the authorisation status of service providers through the appropriate regulator rather than relying on general claims that a company is licensed or regulated.
Anti-Money Laundering and Sanctions Risk
Digital-asset transactions may involve overseas counterparties, self-hosted wallets, and intermediaries whose identities are not immediately clear.
Depending on the activity and applicable obligations, businesses may need customer verification, sanctions screening, transaction monitoring, and suspicious-activity escalation procedures.
A blockchain transaction record alone does not establish that the underlying payment is legitimate.
The Financial Action Task Force has also highlighted financial-crime vulnerabilities involving stablecoins, virtual-asset service providers, and unhosted wallets.
Businesses should therefore assess their actual financial-crime exposure and implement controls proportionate to their activities and legal obligations.
Official source: Financial Action Task Force Virtual Assets Guidance
https://www.fatf-gafi.org/en/topics/virtual-assets.html
Issuer and Reserve Risk
The reliability of a stablecoin depends partly on the financial and operational arrangements supporting its value.
Businesses should consider the issuer's regulatory status, reserve composition, redemption rights, external assurance arrangements, and exposure to banking counterparties.
A stablecoin described as being backed by conventional currency should not be assumed to provide the same protections as money held directly in a bank account.
Loss of Peg and Liquidity Risk
A stablecoin can temporarily or permanently trade below its intended reference value.
Such changes may arise from market uncertainty, reserve concerns, liquidity shortages, or redemption difficulties.
A business receiving stablecoins should define its maximum permitted exposure and establish procedures for responding to significant price deviations.
Wallet Security and Cybersecurity Risk
Digital wallets require suitable access controls and security procedures.
Private-key theft, incorrect wallet addresses, unauthorised transactions, and technology failures can result in substantial financial losses.
Businesses should consider restricted access, multiple approval levels, transaction limits, recovery arrangements, and incident-response procedures.
Accounting and UAE Tax Risk
Stablecoin transactions still require accurate financial records.
Finance teams need to determine how receipts, transfers, conversion proceeds, transaction fees, and outstanding balances should be recognised.
The appropriate Accounting treatment depends on the transaction characteristics and relevant financial reporting standards.
UAE VAT and Corporate Tax implications should also be assessed based on the actual business activity.
Businesses should not assume that using digital tokens removes conventional invoicing, accounting, or tax responsibilities.
How Should UAE Businesses Prepare Before Accepting Stablecoin Payments?
UAE businesses should begin with a structured feasibility assessment covering legal permissions, payment providers, financial controls, and accounting procedures. The purpose is to determine whether the proposed arrangement is commercially useful and legally permitted. This review should be completed before committing to payment technology, digital-wallet infrastructure, or long-term service agreements.
Business and Documentation Checklist
Company Registration Documents
Maintain the trade licence, company registration details, and evidence of the legal entity responsible for the transactions.
Regulatory Jurisdiction
Confirm whether the relevant activity falls within mainland UAE, DIFC, ADGM, or another applicable regulatory framework.
Payment Activity Description
Document the nature of the proposed transactions, the counterparties involved, and the intended commercial purpose.
Stablecoin and Issuer Information
Identify the proposed token, reference currency, issuing entity, reserve arrangements, and redemption conditions.
Provider Authorisation
Verify whether the relevant payment, custody, and conversion providers hold the licences or registrations required for their activities.
Customer and Counterparty Records
Maintain appropriate customer, supplier, and transaction information consistent with applicable legal obligations.
AML and Sanctions Procedures
Document the screening, monitoring, escalation, and reporting controls appropriate to the business model.
Banking and Conversion Arrangements
Confirm how permitted digital-token receipts will be converted, settled, and transferred into corporate bank accounts.
Wallet Security Policies
Establish access permissions, transaction authorisations, recovery procedures, and incident-response responsibilities.
Accounting Procedures
Define how transactions will be recorded, valued, reconciled, and supported by invoices or other documentation.
Treasury Risk Limits
Determine whether the company will retain any stablecoin balances and establish suitable exposure limits.
Professional Review
Obtain relevant legal, regulatory, tax, and accounting advice before implementing arrangements that create uncertainty or material financial exposure.
What Common Mistakes Should UAE Business Owners Avoid?
One frequent mistake is treating stablecoin payments as a simple technology upgrade rather than a regulated financial arrangement. Other problems arise when businesses choose providers without verifying authorisations, overlook transaction costs, or fail to establish accounting procedures. These weaknesses can create financial losses, operational disruption, or regulatory exposure.
Assuming Every Stablecoin Is Acceptable
A stablecoin being popular internationally does not establish that it may legally be used for a particular UAE commercial transaction.
Token classification, issuance arrangements, and the intended use all matter.
Overlooking Regulatory Differences
A business operating in Dubai mainland may face different requirements from an entity regulated within ADGM or DIFC.
Management should avoid applying one jurisdiction's permissions to a different business structure.
Selecting Providers Without Verification
A provider may be regulated for one activity but not authorised for another.
Businesses should verify the specific legal entity, licence category, and permitted services.
Ignoring Total Transaction Costs
Blockchain network charges represent only part of the total settlement expense.
Conversion, custody, compliance, system integration, and banking costs should also be included in financial comparisons.
Failing to Maintain Reliable Records
Digital-wallet statements alone may not provide all documentation necessary for accounting, audit, and tax purposes.
Transactions should be supported by appropriate commercial records and reconciliation procedures.
Holding Excessive Stablecoin Balances
Businesses should avoid retaining significant stablecoin exposure without documented treasury policies and risk assessments.
Example 2: Abu Dhabi Trading Business
A fictional Abu Dhabi trading company considers receiving stablecoin payments from overseas buyers.
Management initially views the arrangement as a way to accelerate international settlement.
During its internal review, the finance team identifies uncertainties regarding merchant acceptance, token conversion, banking arrangements, and financial reporting.
The company decides to clarify the regulatory position and introduce documented controls before proceeding.
This approach allows management to assess the commercial proposal without assuming that faster blockchain transfers automatically justify the operational risks.
Should UAE SMEs Adopt Stablecoin Payments?
Stablecoin payments may suit selected UAE SMEs where there is a clear commercial benefit and the proposed transaction is legally permitted. Businesses with straightforward domestic transactions may find that existing banking solutions remain more practical. The decision should reflect settlement requirements, compliance costs, financial exposure, and the company's operational readiness.
Commercial Feasibility
Management should identify the payment problem it intends to solve and calculate the expected benefit.
Potential improvements may involve settlement time, payment transparency, or operational efficiency.
Regulatory Feasibility
The company should establish that the specific token, transaction, provider, and business activity are permitted within the applicable legal framework.
Financial Feasibility
The finance team should compare existing banking expenses with the total cost of the proposed stablecoin process.
Operational Readiness
Businesses should assess whether they have adequate systems, personnel, security procedures, and accounting controls to manage digital-token transactions responsibly.
Long-Term Sustainability
Stablecoin payment arrangements should be reviewed periodically as regulatory requirements, provider conditions, and commercial circumstances change.
A faster payment method only creates business value when the company can receive, verify, reconcile, and use the funds within an appropriate compliance framework. — Editorial observation, The Consulting Journal
How Can KPM Global Services UAE Assist Businesses?
Stablecoin payment decisions often require coordination between finance, compliance, tax, accounting, and technology teams.
KPM Global Services UAE can support businesses in reviewing the financial and operational implications of proposed digital-asset transactions.
Accounting and Financial Reporting
Reviewing transaction-recording processes, reconciliation procedures, and reporting requirements for digital-asset activities.
Financial Process Assessment
Evaluating how proposed payment arrangements affect treasury management, cash flow, internal controls, and financial administration.
Tax and Documentation Review
Identifying potential UAE VAT and Corporate Tax considerations and supporting the organisation of relevant commercial documentation.
Internal Controls and Operational Readiness
Helping businesses assess financial approval procedures, transaction records, reporting workflows, and control responsibilities.
Coordination With Specialist Advisers
Where regulatory interpretation or formal legal assessment is required, businesses should work with appropriately qualified UAE legal and regulatory professionals.
The aim is to support informed financial decisions based on the company's commercial needs and applicable obligations.
Final Advisory Perspective
Stablecoin payments may become increasingly relevant to international commerce and digital financial operations in the UAE.
For some businesses, the technology offers potential improvements in settlement flexibility, payment tracking, and financial automation.
However, these benefits should not be separated from regulatory responsibilities.
The UAE distinguishes between different payment-token categories, service providers, and regulated activities. The availability of a digital token does not automatically establish permission to use it for ordinary commercial payments.
Before adoption, business owners should confirm the applicable regulatory position, assess the commercial economics, verify service providers, and establish suitable accounting and risk-management procedures.
Stablecoins should be evaluated as regulated financial infrastructure rather than simply another payment option.
Regulatory context reviewed: 8 October 2026. Applicable rules, regulatory interpretations, provider authorisations, and approved-token lists may change.
This article is for informational purposes and does not constitute legal, tax, accounting, or financial advice.
Questions and answers
Q: Can businesses legally accept stablecoin payments in the UAE?
A: Stablecoin acceptance is permitted only within the applicable UAE regulatory framework. Under the CBUAE Payment Token Services Regulation, merchants outside Financial Free Zones are subject to restrictions on accepting virtual assets for goods and services. Businesses should confirm the token category, issuer status, jurisdiction, and transaction purpose before accepting payments.
Q: Can a Dubai company accept USDT or USDC payments from customers?
A: A Dubai company should not assume that USDT or USDC can be accepted for ordinary goods and services simply because these tokens are widely used internationally. The CBUAE framework imposes specific merchant-acceptance restrictions, and other regulatory rules may apply depending on the entity and activity. Transaction-specific professional advice is recommended before implementation.
Q: Do UAE businesses need a licence to use stablecoins?
A: Licensing requirements depend on the nature of the business activity. Merely receiving a legally permitted payment is different from issuing payment tokens, providing custody, arranging transfers, or conducting conversion services. Companies performing regulated Payment Token Services generally require the appropriate authorisation within the applicable regulatory framework.
Q: Are stablecoin payments cheaper and faster than international bank transfers?
A: Stablecoins may enable quicker blockchain transfers and reduce certain intermediary costs. However, conversion charges, network fees, compliance requirements, custody arrangements, and bank withdrawals can affect the overall result. Businesses should compare complete settlement costs and timelines rather than looking only at the blockchain transaction.
Q: How should UAE companies account for stablecoin transactions?
A: UAE companies should maintain reliable records of stablecoin receipts, transfers, conversions, fees, and outstanding balances. Appropriate recognition, measurement, and tax treatment depend on the transaction circumstances and applicable accounting standards. Finance teams should establish documented reconciliation procedures and obtain specialist guidance where necessary.
More in Crypto
View all Crypto →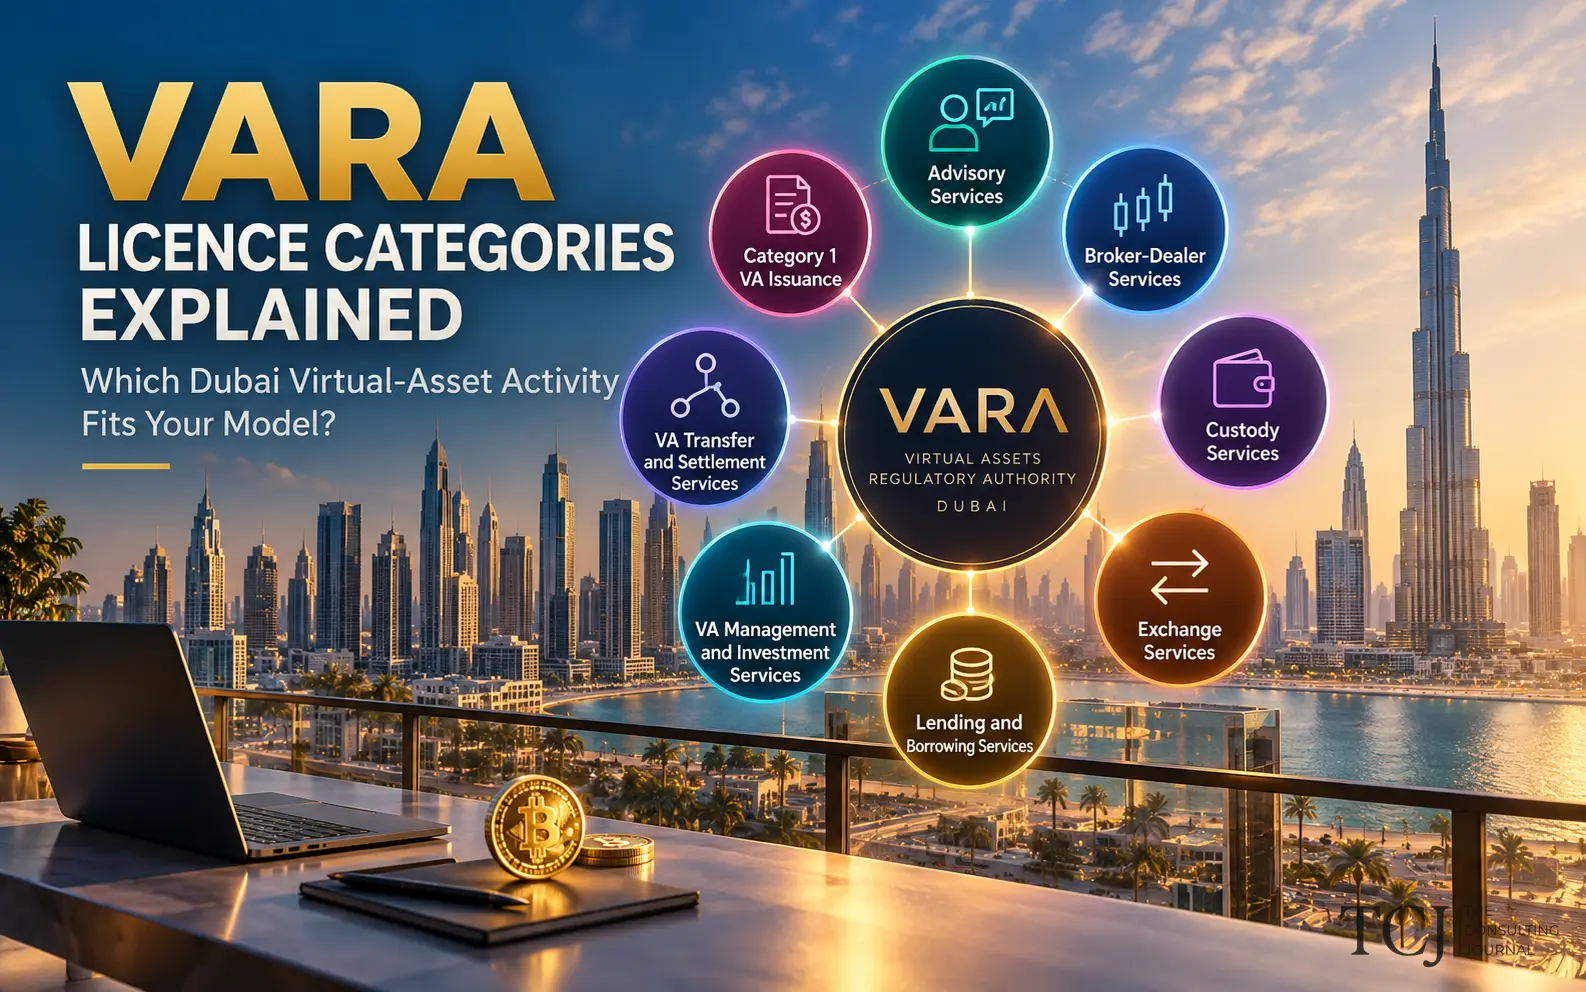
VARA Licence Categories Explained: Which Dubai Virtual-Asset Activity Fits Your Model?
Dubai’s virtual-asset framework is activity based, meaning there is no single generic crypto licence. This guide explains the eight VARA licence categories, how different business models may fall within them, and what founders should assess before launching a virtual-asset business in Dubai.
When Does a Spanish Digital-Asset Business Need a VARA Licence in Dubai?
Spanish crypto and digital-asset firms expanding to Dubai need to assess activities, entity location, marketing and licensing separately. This guide explains when VARA may apply, how MiCA fits, and what businesses should prepare before launch.
Blockchain Opportunities for Italian Luxury and Product Authentication
Italian luxury brands can use blockchain to strengthen product authentication, provenance, Digital Product Passport readiness, resale verification, supplier traceability, and long-term product identity.